Optimization of Special Risk Insurances and Mortgages
Formulating and solving a linear programming problem is essential for determining the optimal number of special risk insurances and mortgages to sell. The primary goal is to maximize profit while adhering to specific constraints related to underwriting, administration, and claims limits. The objective function is defined as maximizing (5x_1 + 2x_2), where (x_1) is the number of risk insurances and (x_2) is the number of mortgages sold. By employing the intersecting line method, the optimal solutions found are (x_1 = 600) and (x_2 = 300), leading to a maximum profit of $3600.

Optimization of Special Risk Insurances and Mortgages
E N D
Presentation Transcript
1. Assignment 1
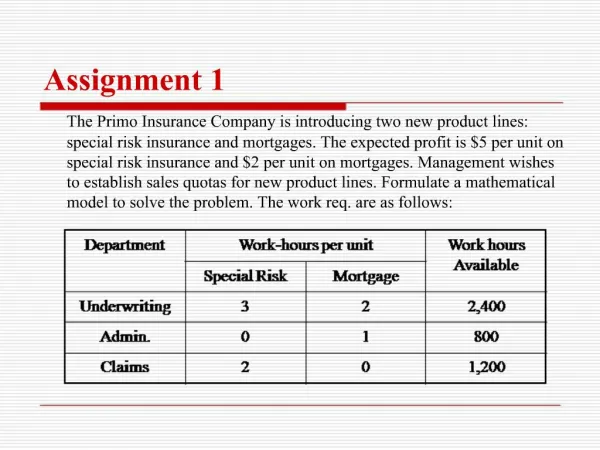
2. Problem Formulation x1 = number of special risk insurances to be sold
x2 = number of mortgages to be sold
Obj: Max(5x1 + 2x2)
s.t.: 3x1 + 2x2 <= 2400 (Underwriting dept.)
x2 <= 800 (Admin)
2x1 <= 1200 (Claims)
x1, x2 >= 0 (Non-negativity)
3. Graph
4. Intersecting Line Method The two lines that meet at the optimal point are:
3x1 + 2x2 = 2400
2x1 = 1200
The equations are known as ‘binding constraints’.
Solving for x1 and x2 in the two equations:
x1 = 600; x2 = 300
Therefore, objective function value (z)
= 5x1 + 2x2 = 5(600) + 2(300) = $3600